CPA and Bookkeeping El Paso Alternative.The county half of one percent.
The sales tax stack is a public fact with two halves that people drop, and the return on the 20th is where the drop becomes a problem. It names the work.
See the stack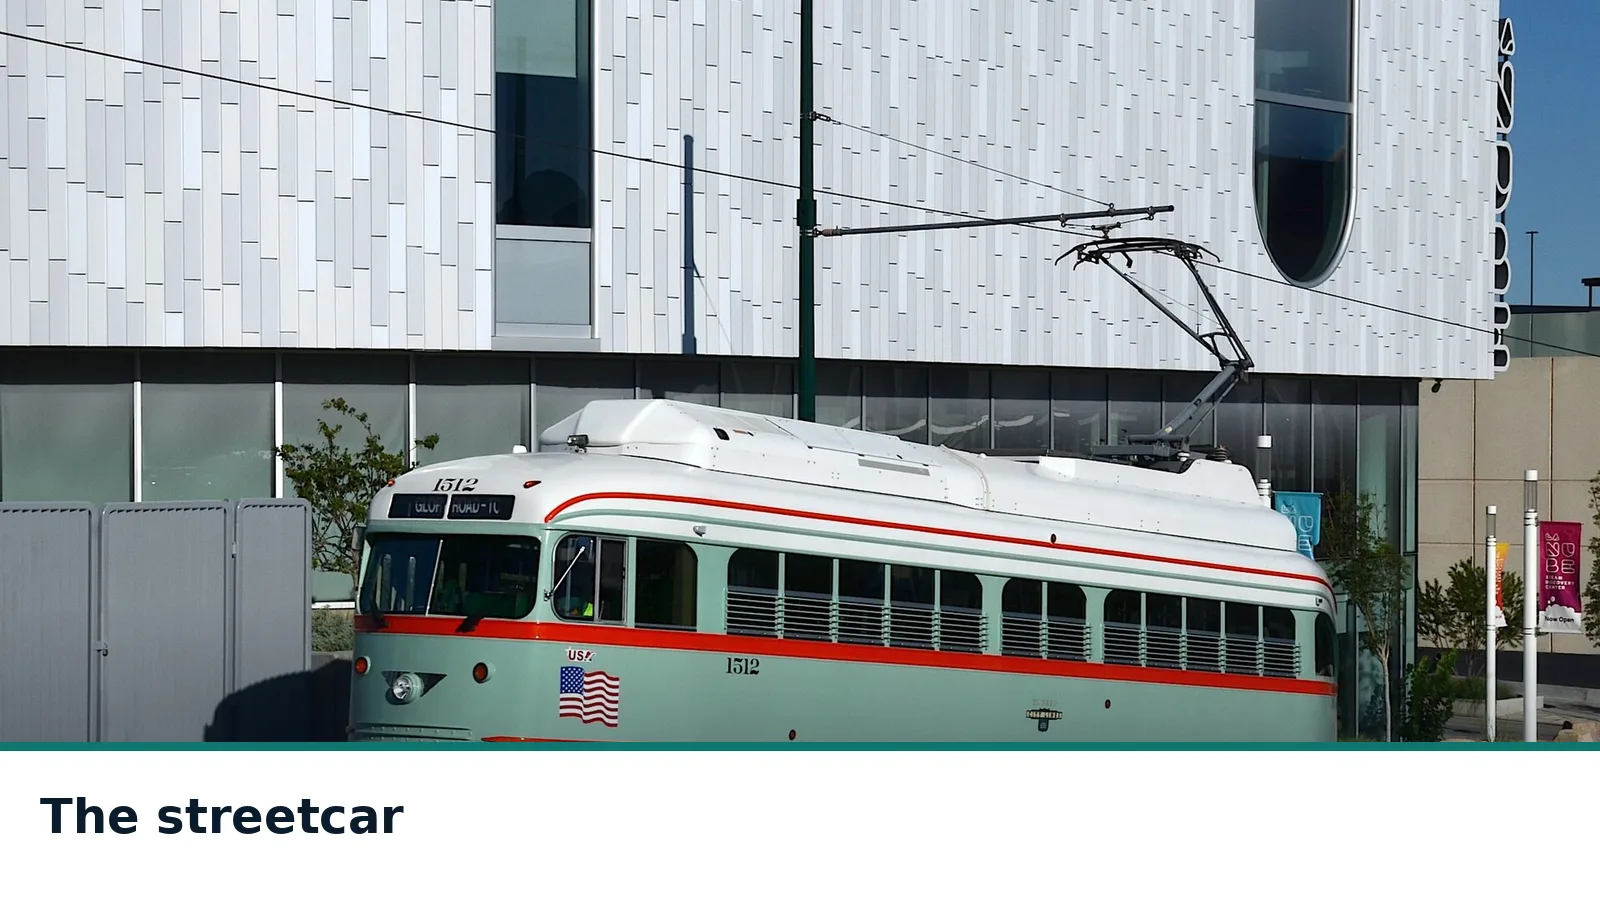
The stack people remember wrong
Read this part
The combined rate people quote is 8.25 percent. That number is a ceiling the state set, and it is also a sum. The state takes 6.25 percent. The city takes 1 percent. The county takes half of one percent. A transit piece takes another half of one percent inside the city. Add them and you are at the ceiling. Forget a half and you are not at the ceiling, and the money you collected from customers will not match the return you file.
The county half is one of the county sales taxes in Texas, and the revenue is dedicated to property tax relief. That purpose does not change how you charge it. You still collect it on a taxable sale. You still report it. The purpose matters when someone asks why the county is in the stack at all. The answer is not a local quirk you can round away. It is a tax with a job, and the job is written down by the comptroller.
The transit half has a different map. It took effect years ago and it applies inside the city, not across every corner of the county. A sale in the city carries both halves. A sale outside the city may carry the county half and not the transit half. If your customers are in both places, one rate for the whole file is how you end up short or long. We ask where the sale happened before we accept a single rate on the report.
The 20th, and the hour
Read this part
The state wants the sales tax return on the 20th. For a monthly filer that 20th belongs to the month after the one being reported. A quarterly filer sends the 20th of April, July, October, and January, for the quarter that just ended. Those dates are state dates. They are kept in Central time. This city is the major one in Texas that keeps Mountain Time. On the last day, the wall clock is an hour ahead of the feeling and an hour behind the deadline. People miss the return because the evening still looks early.
We do not file in that evening. The return is built from the closed month, and the closed month should have been done before the 20th was a crisis. If the books are open on the 19th, the crisis is the books, not the clock. We would rather file a true return in the morning than a guessed return at night. A guessed return is a second project, because it has to be fixed.
There is a walk-in comptroller office in town, open Monday and Wednesday from 9 to 4 and Friday from 8 to noon. We are not sending you there with a box of paper. We mention it because the dates are real and the state is not abstract. Most of what we file goes in electronically from the books. The office is a reminder that a person can still ask a question. Your question to us should arrive before the morning of the 20th.
What the books have to show
Read this part
A sales tax return is a summary of taxable sales, exempt sales, and the tax collected. The books have to be able to produce that summary without a heroic afternoon. If taxable and exempt live in the same account, the return is a guess wearing a total. We separate them. If the tax collected is buried inside sales, we pull it out, because the tax was never your income. Customers paid it. You are holding it. Holding it in the sales account makes the month look richer than it was.
Two currencies make this worse if you are not careful. Tax is computed on the taxable sale in the money of that sale, then it has to meet a return that is filed in dollars. The bridge line is not only for the income. It is also for the tax you collected in one money and will remit in another. We do not let the tax ride inside a blended deposit and hope the 20th sorts it out. The 20th does not sort. It asks for a number.
Use tax is the other side. Something you bought for the business without tax, because the vendor was elsewhere, can still be taxable to you. The zone, a resale, and a genuine exemption are reasons. A forgotten checkout button is not a reason. We look at large purchases in the month and we ask. The question is cheaper than a notice.
Property tax relief is not your filing
Read this part
The county half is dedicated to property tax relief. That sentence is about the county's budget, not about a discount on your sales tax return. You do not get to skip the half because you also pay property tax. They are different taxes with different calendars. Property bills go out in October. They are due at the end of January. They are delinquent on the first of February. The sales tax half is due with the return on the 20th. Mixing the two stories is how an owner decides, wrongly, that one payment covered both.
We keep them in different places in the books. The sales tax you collected sits as an amount you owe until you remit it. The property tax you owe sits with the bills that arrive in October, accrued when the year has earned it, paid when you pay it. A reader of the statements should be able to tell the two apart without a guide. If they cannot, the statements are not finished.
When a property bill arrives, we read it in that month. October is early enough to matter. A bill that waits until January to be noticed has already lost the months when the year could still be changed. The device on the home names October and January for that reason. The half described here is collected with sales tax, kept apart from the October property bill. The property bill is the reason the county collects the half. Both dates belong on one calendar, in two lines, not in one blur.
A streetcar and a deposit
Read this part
Every Texan can picture a streetcar coming back through a downtown. The one on Santa Fe Street does that ride again. A fare and a deposit are a tiny version of the month we are talking about. The ride is one date. The money in the account may be another. We date the bank. The pleasure of the ride does not choose the month.
We have not stood on that corner to watch it. The picture is enough, and the habit is the point. Card payments, ticket sales, and a Friday night at the ballpark all have the same shape. The feeling is this month. The deposit might be the next. The return on the 20th will not honor the feeling. It will honor the date. We write the date.
What a missed half does
Read this part
If you collected 8.25 percent and you remit less, you are holding money that was never yours, and the return will not match the deposits forever. The mismatch often hides for a few months inside growth. Then a reconciliation of the tax payable account shows a balance that has been climbing. That balance is not a mystery. It is the half, or the hour, or the exempt sales that were not exempt. We would rather find it in the first reconciliation than in a letter.
If you collected less than you should have, the opposite problem appears. You owe tax you did not charge. The customer is gone. The margin eats it. This is the one that stings, and it is the one that comes from using a rate you remembered instead of a rate you looked up for the place of the sale. We look it up. Memory is not a compliance system.
Either way, the fix is the same shape. Separate the tax from sales. Separate the city from the county edge. File from a closed month. Do it in the morning of a day that is not the last evening. None of that is dramatic. Drama is what you get when the letter arrives. We are in the business of the undramatic month.
How we want the file set up
Read this part
The chart of accounts should have a place for tax collected, a place for tax remitted, and a place for use tax you still owe. It should not have one bucket called taxes where sales tax, property tax, and a franchise report all nap together. Those three have different due dates and different meanings. A bucket hides the one that is late.
Your provider runs payday. Sales tax is not payday. We still want the payroll reports, because taxable wages and the sales tax return sometimes get confused in a small file when the same person is doing both on the same afternoon. We keep them apart. Payday is set up so the provider's numbers can be recorded. The sales tax return is built from sales. If those two ever depend on each other, we want to know why, in a sentence, before we file.
The first call goes better when the latest sales tax return and a month you trust are both in front of you. We will say whether the stack on the return matches the stack you collected. If it does, the work is to keep it that way. If it does not, the work is a correction and a habit. Both are ordinary. Neither requires a speech about the border. The border makes two currencies. The stack is a Texas fact on top of that. We can hold both ideas at once.
Send the return you filed

You will be talking to the Steven Palmieri practice.